Variance Mapping for Daily Multi-Sport Portfolio Refinement
Alex Baumann · Aug 19, 2026
Variance Mapping for Daily Multi-Sport Portfolio Refinement
Statistical variance plays a central role in how outcomes unfold across multi-sport betting portfolios, and analysts track these fluctuations through historical datasets to adjust selection criteria each day. Data compiled from major leagues indicates that variance levels shift noticeably between football, basketball, and tennis markets, with football showing higher standard deviations in goal margins during August fixtures while basketball exhibits steadier point spreads in conference play. Observers note that those who monitor these patterns often combine rolling averages with standard deviation calculations to filter selections before finalizing daily lineups.
Core Concepts Behind Variance Tracking
Researchers define variance as the spread of actual results around expected values, and in betting contexts this metric helps quantify how far real returns deviate from modeled probabilities. Studies from academic institutions have applied this approach to large sample sets covering multiple seasons, revealing that portfolios mixing high-variance sports with lower-variance ones can stabilize overall bankroll movement when position sizes are scaled accordingly. Those who have examined league-specific data find that August schedules introduce additional variables, such as fixture congestion in European football and preseason adjustments in American basketball, both of which widen variance bands.
Calculations typically begin with expected value formulas, then layer in variance estimates derived from past match results; the resulting figures guide whether a selection meets minimum stability thresholds for inclusion. Industry reports released in mid-2026 highlight that operators in several jurisdictions now supply aggregated performance data that supports these calculations, allowing independent analysts to update models weekly without relying solely on proprietary records.
Application Across Different Sports
Football markets tend to produce wider variance distributions because low-scoring games amplify the impact of single events, whereas basketball outcomes cluster more tightly around team efficiency ratings. Tennis adds another dimension through surface-specific and fatigue-related swings that researchers quantify using match-duration statistics. Analysts who build daily portfolios often assign separate variance weights to each sport and then run Monte Carlo simulations to test how the combined set performs under randomized outcome sequences.
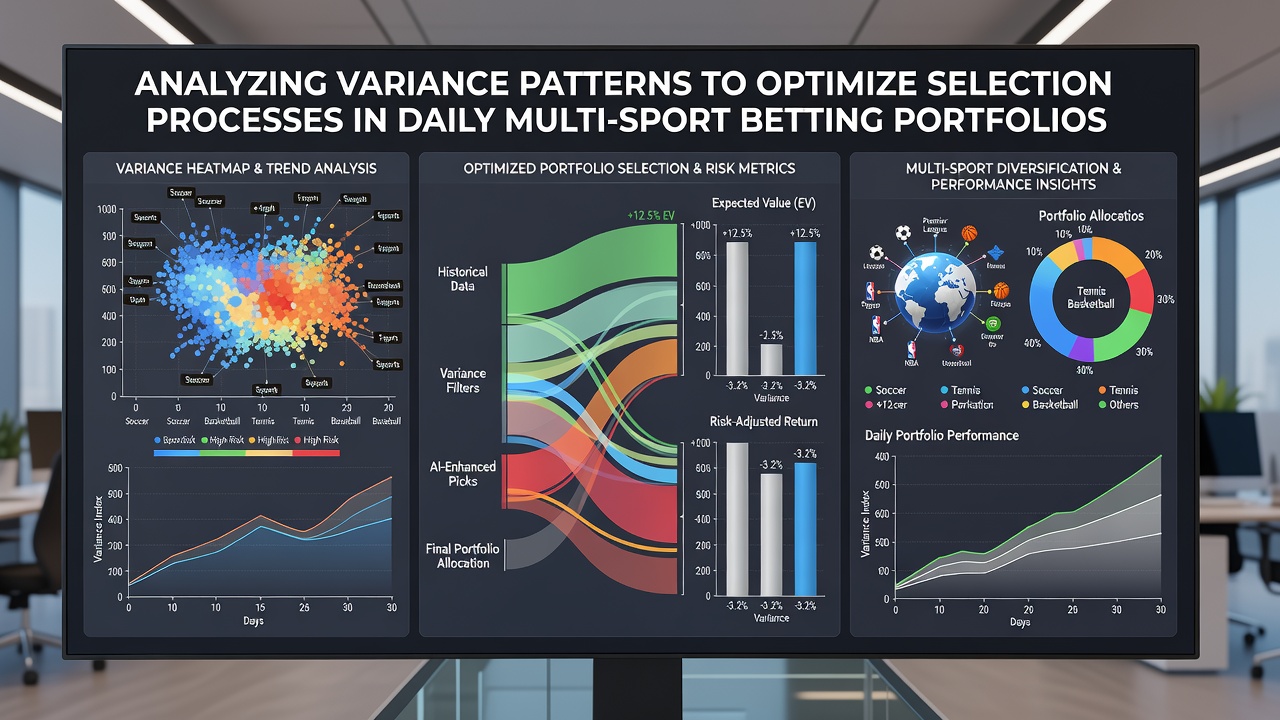
One documented case involved a research team that tracked three consecutive August periods and observed that variance spikes in football coincided with early-season squad rotations, prompting them to reduce exposure on those dates while maintaining basketball volume. Similar work by European academic groups has shown that cross-sport correlation coefficients remain low enough to support diversification benefits, provided variance filters are applied consistently.
Methods for Refining Selection Criteria
Practitioners start by compiling rolling 30-day and 90-day variance figures for each market type, then apply thresholds that exclude selections falling outside two standard deviations of historical norms. This process integrates with bankroll allocation rules that scale stake sizes inversely with measured variance, thereby limiting drawdown exposure on high-fluctuation days. Data from regulatory filings in Australia and Canada demonstrates that operators using comparable filtering systems report more predictable revenue streams across mixed-sport offerings.
Additional layers include tracking variance trends by time of day and by betting market liquidity, since thinner markets in lower-tier tennis events often display larger deviations than main-draw matches. Analysts update these parameters daily using automated scripts that pull fresh results and recalculate coefficients, ensuring the selection process remains responsive to the latest patterns. Reports from the National Council on Problem Gambling in the United States indicate that structured variance monitoring forms part of broader responsible-gambling toolkits offered by several platforms.
Data Sources and Ongoing Adjustments
Public league databases supply the raw inputs required for variance calculations, while peer-reviewed papers supply validation benchmarks for model accuracy. A 2025 study published through the International Gambling Studies journal examined multi-sport datasets spanning five years and confirmed that variance-adjusted portfolios reduced maximum drawdowns by measurable margins compared with unfiltered approaches. In August 2026, several European research consortia released updated seasonal benchmarks that analysts now incorporate into live models.
Those maintaining daily portfolios also monitor external factors such as weather impacts on outdoor sports and travel schedules that influence basketball performance variance. These variables are folded into the same statistical framework, allowing consistent comparison across all included sports. Continued refinement occurs through back-testing against archived results, with successful adjustments retained and unsuccessful ones discarded after statistical review.
Conclusion
Variance analysis supplies a structured method for evaluating and refining selections within daily multi-sport betting portfolios, drawing on established statistical techniques and publicly available datasets. Observers who apply these methods report more stable performance metrics over extended periods, particularly when August scheduling variables are accounted for in the models. Ongoing data releases from academic and regulatory bodies continue to support incremental improvements to these analytical frameworks.