UK's Betting Surge: Digital Shifts Fueling New Trends in Sports Wagering Markets
Riley Krüger · Aug 19, 2026
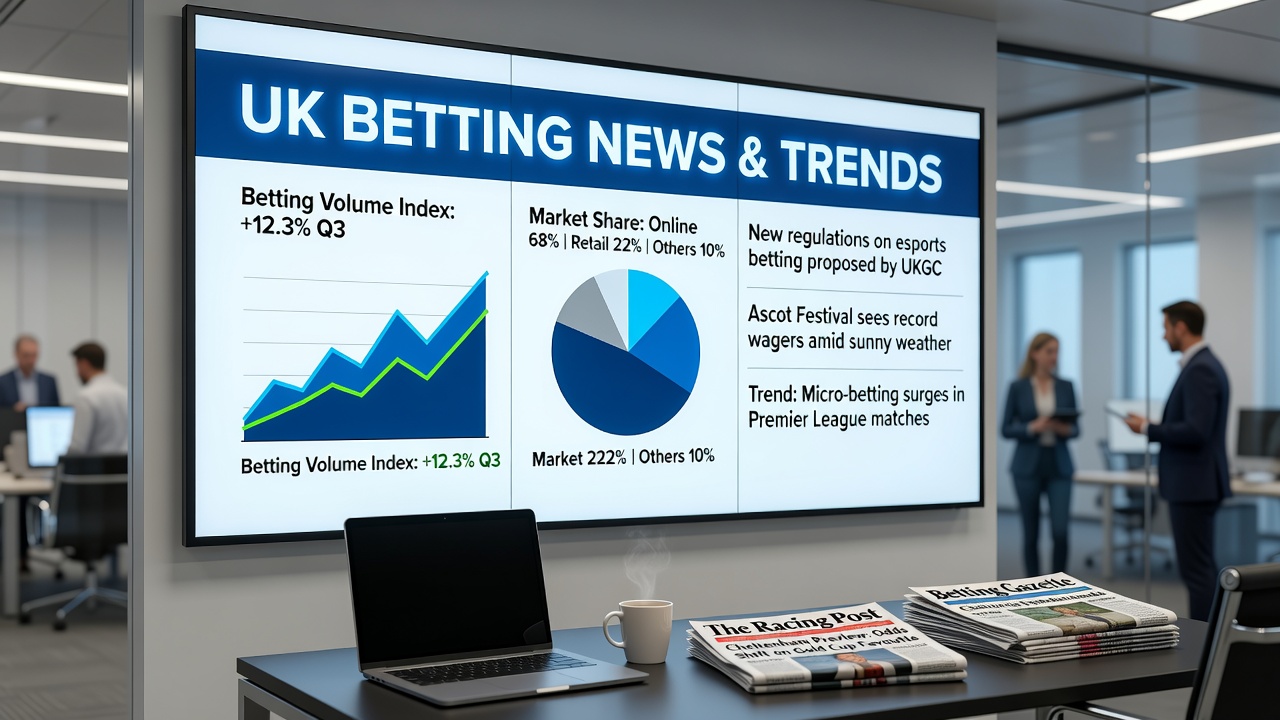
UK Gambling Commission Introduces Financial Risk Checks for High-Spending Online Gamblers
The UK Gambling Commission has unveiled fresh requirements that mandate financial risk assessments for online gamblers who exceed spending limits of £1,000 within any 24-hour window or £3,000 across a rolling 90-day period, with reduced thresholds applying to those under 25. These checks draw on credit reference agency information yet leave credit scores untouched, and the entire framework begins rolling out gradually this summer starting with the biggest operators at elevated initial thresholds such as £5,000 for adults over 25. Less than 0.5 percent of customers face immediate impact under the phased approach, which spreads implementation across months rather than imposing sudden nationwide changes.Core Elements of the Assessment Rules
Operators must evaluate a gambler's financial situation once spending crosses the defined daily or quarterly marks, using data from credit agencies to flag potential difficulties without triggering score alterations. For players under 25 the limits sit lower from the outset, reflecting separate vulnerability considerations built into the policy. The process stays limited to high spenders and avoids routine checks on the wider customer base, keeping the focus narrow and targeted.
Initial thresholds remain higher during early stages so the largest firms can test systems before broader application, and this setup means most accounts continue without intervention even after summer launch. Those who've studied similar regulatory shifts note how such staging reduces disruption while still advancing the core goals.
Timeline and Scope of the Rollout
Implementation starts this summer with major operators handling the first wave at the £5,000 level for over-25s, then steps down toward the full £1,000 and £3,000 figures over subsequent periods. The gradual pace ensures smaller platforms receive later deadlines, while data collection remains consistent across all participating sites once thresholds activate. Observers note that the less-than-0.5-percent coverage at launch keeps operational demands manageable and limits customer friction during transition.
Purpose and Expected Coverage
The measures seek to spot high spenders who may encounter financial strain, drawing on patterns visible in credit records to prompt earlier intervention where needed. According to the Gambling Survey for Great Britain, such targeted reviews align with broader efforts to monitor activity among those placing larger bets, yet the rules deliberately exclude the majority of accounts that stay below the spending lines. Experts have observed that this selective method concentrates resources where risk indicators appear strongest, while the credit-data method avoids any direct score impact that could otherwise concern users.
Industry Group Responses
Industry groups have voiced concerns that the new checks could divert some users toward unregulated black-market sites, citing potential inconvenience as a key factor in that shift. These organizations point to the thresholds themselves as possible triggers for customers seeking fewer hurdles elsewhere, although the Commission maintains the assessments remain proportionate and data-protected. The criticism centers on implementation details rather than outright rejection of risk identification, and operators continue preparing systems under the phased schedule.
Conclusion
The UK Gambling Commission's approach combines defined spending triggers with credit-agency sourcing and a measured rollout that begins this summer at higher starting points, affecting a small initial share of accounts while addressing financial-difficulty signals among top spenders. Industry feedback highlights black-market risks without altering the core requirements, leaving operators to adapt within the timeline set by regulators.